If you’ve ever stared at an insurance website and felt your brain slowly melt, you’re not alone. This beginner friendly insurance guide for self employed business owners exists because I spent my first year freelancing with zero coverage and a prayer. That was dumb. When a client threatened to sue me over a missed deadline, I realized I couldn’t keep winging it. Insurance felt overwhelming until I actually sat down, made mistakes, learned from them, and figured out what mattered.
Why Self Employed Business Owners Can’t Skip Insurance
Here’s the thing nobody tells you when you file that first Schedule C: you are the business. There’s no corporate shield automatically protecting your personal assets. If a client slips at your home office, if your advice causes someone a financial loss, if your laptop gets stolen with sensitive data on it, that’s all on you.
I used to think insurance was something only “real” businesses needed. Businesses with warehouses and employees and fleets of trucks. Then a freelance designer friend got sued for $15,000 over a logo that allegedly infringed on a trademark. She had no coverage. She paid out of pocket, and it nearly bankrupted her side business.
General liability insurance is where most self employed people should start, and it’s shockingly affordable. I pay around $30 a month for mine through Hiscox. That covers bodily injury, property damage, and some advertising claims. For the cost of a few coffee runs, you get peace of mind that one bad day won’t wipe you out.
Step 1: Figure Out What You Actually Need
Not every self employed person needs the same policies. A dog walker has very different risks than a freelance accountant. Before you buy anything, sit down and honestly think about your worst case scenarios.
Ask yourself three questions. What could physically go wrong during my work? What could financially go wrong because of my work? And what personal safety nets disappeared when I left traditional employment?
That last question hit me hard. When I left my 9 to 5, I lost health insurance, disability coverage, and life insurance all at once. I was so focused on landing clients that I forgot I’d stripped away my entire safety net. Making a simple list of your risks and your gaps will save you from buying policies you don’t need while skipping ones you desperately do.
Step 2: Understand the Core Policy Types
This is the part that used to confuse me the most, so I’m going to keep it simple. There are really only a handful of policy types that matter for most self employed folks.
General Liability Insurance
This covers you when someone gets hurt because of your business or when you damage someone else’s property. If a client visits your workspace and trips over a cord, general liability handles it. Most small business owners pay between $300 and $600 per year. I got my policy through Hiscox, but NEXT Insurance and Thimble are also solid options for solopreneurs.
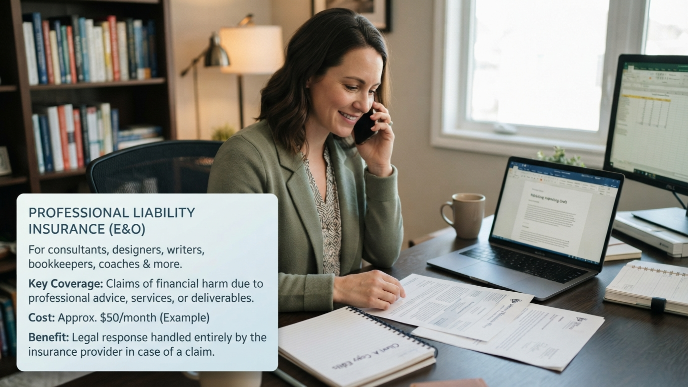
Professional Liability Insurance (Errors and Omissions)
If your work involves giving advice, creating deliverables, or providing any kind of professional service, this is the one you can’t ignore. It covers you when a client claims your work caused them financial harm. Consultants, designers, writers, bookkeepers, and coaches all need this. My policy runs about $50 a month, and I’ve already used it once when a client claimed my marketing copy led to a compliance issue. The insurance company handled the legal response entirely.
Health Insurance
This is the big scary one. Without an employer plan, you’re on your own. I spent my first open enrollment period on Healthcare.gov comparing plans for about six hours. My honest advice: pick a plan with a deductible you can actually afford to pay, not just the cheapest monthly premium. A $7,000 deductible sounds great until you actually need surgery.
If your income qualifies, you might get subsidies through the ACA marketplace. I saved about $400 a month in subsidies my first year because my self employment income was modest. Also look into health care sharing ministries or short term plans if you’re between coverage periods, but read the fine print carefully.
Disability Insurance
Nobody talks about this, and it’s arguably the most important one for self employed people. If you break your arm and can’t work for three months, who pays your bills? Nobody. That’s who. Long term disability insurance replaces a portion of your income if illness or injury keeps you from working. I got mine through Breeze, and it costs me about $80 a month. Worth every penny for the “what if” protection.
Business Property Insurance
If you work from home, your homeowner’s or renter’s insurance probably doesn’t cover your business equipment. I learned this the hard way when a pipe burst and ruined my desk setup. My renter’s insurance denied the claim because the equipment was used for business purposes. A separate business property policy or a rider on your existing policy fixes this. It typically costs $100 to $300 per year.
Step 3: Know Where to Shop (Without Getting Ripped Off)
The insurance shopping experience for self employed people has gotten way better in the last few years. You don’t need to sit in an agent’s office for two hours anymore.
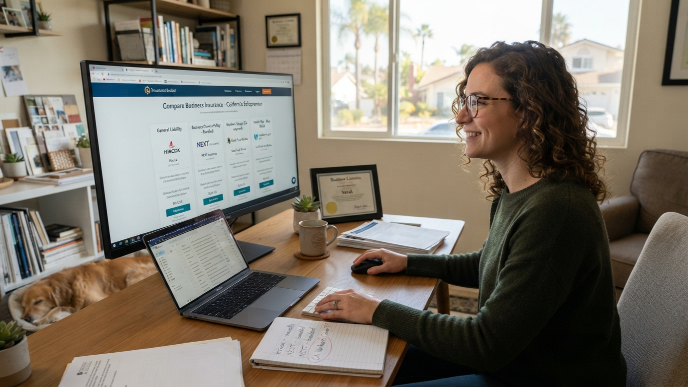
Online-first providers like Hiscox, NEXT Insurance, and Thimble let you get quotes in minutes. I’ve used Hiscox for three years now and the experience has been smooth. NEXT Insurance is great if you want everything bundled, and Thimble offers pay-per-day coverage which is perfect if you only need insurance for specific gigs or events.
For health insurance, stick with Healthcare.gov during open enrollment or use a broker. I like using a broker because they don’t cost you anything extra, the insurance company pays their commission, and they can compare plans across multiple carriers. I found mine through the National Association of Health Underwriters directory.
For disability and life insurance, Breeze and Ladder are both straightforward. Policygenius is also a good comparison tool if you want to see multiple quotes side by side without entering your phone number twelve times.
One tip I wish someone had given me: always check whether your state or city requires specific coverage. Some states mandate workers’ comp even for solopreneurs who hire occasional subcontractors. My state (California) required it when I brought on a part time assistant, and I didn’t realize it until I was technically breaking the law.
Step 4: Set Your Budget Without Overbuying
Insurance companies will happily sell you every policy under the sun. You don’t need all of them right away. When I started, I prioritized in this order:
- Health insurance (because medical debt destroys people)
- General liability (because client-facing work carries inherent risk)
- Professional liability (because one lawsuit could end everything)
- Disability insurance (because my income depends on my ability to work)
- Business property coverage (because replacing a $2,000 laptop hurts)
My total monthly insurance spend across all policies is about $620. That sounds like a lot until you realize a single ER visit without insurance costs more than a full year of premiums. I budget it as a fixed business expense and write most of it off on my taxes. Your accountant can help you figure out which premiums are deductible, and FYI, most of them are for self employed people.
Step 5: Review Your Coverage Every Year
Your business changes. Your insurance should change with it. I made the mistake of keeping the same general liability limits for two years even though my revenue had tripled. If something had gone wrong, my coverage would have been embarrassingly inadequate.
Set a calendar reminder every year, maybe around tax time when you’re already thinking about your business finances, to review every policy. Are your revenue numbers accurate? Have you added new services? Did you hire anyone? Are you storing client data differently?
I also recommend keeping a simple spreadsheet with every policy, its renewal date, the monthly cost, and what it covers. It takes twenty minutes to set up and saves you from those panicked moments when you can’t remember if your professional liability covers cyber incidents. Mine didn’t, by the way. I had to add that separately.
Common Mistakes in This Beginner Friendly Insurance Guide
After three years of figuring this out myself and helping two friends set up their coverage, these are the mistakes I see most often.
People assume their personal auto insurance covers business driving. It usually doesn’t. If you drive to meet clients, deliver products, or travel to job sites, you need a commercial auto policy or a business use endorsement on your personal policy.
People skip professional liability because they think “I’m too small to get sued.” You’re not. Anyone can file a claim against you, and defending yourself costs money even if you win.
People buy the cheapest health plan without understanding the network. I almost signed up for a plan that didn’t include a single hospital within 30 miles of my house. Always check the provider directory before you commit.
And the biggest one: people wait until something goes wrong. Insurance doesn’t work retroactively. You can’t buy fire insurance while your house is burning. Get covered before you need it.
Frequently Asked Questions
What insurance do self employed people need first?
Start with health insurance and general liability. Health insurance protects you personally from catastrophic medical costs. General liability covers your business from third party claims. These two form the foundation, and everything else builds on top. Most self employed people can get both set up in a single afternoon for reasonable monthly premiums.
How much does insurance cost for a self employed business owner?
It varies wildly depending on your industry and location, but a rough ballpark is $400 to $800 per month for comprehensive coverage including health, liability, and professional policies. Individual liability policies can be as low as $25 to $50 monthly. Health insurance is usually the biggest expense, especially without employer contributions or ACA subsidies.
Can I deduct insurance premiums on my taxes?
Yes, most self employed business owners can deduct health insurance premiums, liability insurance, and other business-related policy costs. Health insurance premiums get deducted on your personal return as a self employment adjustment. Business policies get deducted as business expenses on Schedule C. Talk to your tax professional for specifics, because rules vary by situation.
Is this beginner friendly insurance guide relevant for freelancers too?
Absolutely. Freelancers are self employed business owners in the eyes of the IRS and insurance companies. Whether you freelance full time or as a side hustle, the same risks apply. If anything, freelancers often need professional liability insurance even more because their work product directly impacts clients. The same policies and shopping strategies apply regardless of what you call yourself.
Do I need insurance if I work from home?
Working from home doesn’t eliminate your business risks. Your homeowner’s or renter’s policy typically excludes business equipment and business liability claims. You still need general liability if clients interact with you, professional liability if you provide services, and a business property rider to protect your work equipment. Home-based businesses actually have some unique coverage gaps worth addressing early.
Conclusion
Getting your insurance sorted as a self employed person isn’t glamorous, but it’s one of those things that separates people who build lasting businesses from people who get wiped out by one bad month. Start with the basics, shop smart, and revisit your coverage every year. What policy are you still putting off buying?