When I first needed a simple insurance guide for freelancers without steady income, every resource I found assumed I had a predictable paycheck. I didn’t. Some months I earned great money. Others, barely enough to cover rent. Figuring out health, liability, and disability coverage while my bank account fluctuated wildly felt impossible. But after six years of freelancing, I’ve finally cracked a system that works, and I’m sharing all of it here.
Why Traditional Insurance Advice Fails Freelancers
Most insurance guides assume you earn the same amount every two weeks. They tell you to set aside a fixed percentage or pick a plan based on your annual salary. That’s useless when your January earnings look nothing like your March earnings.
I remember sitting on the phone with a health insurance rep who kept asking for my “annual household income.” I genuinely did not know the answer. I gave her a rough estimate, and she placed me in a plan that ended up costing way more than I could afford during a slow quarter. That experience taught me something important: freelancers need to approach insurance from a completely different angle.
The core problem is cash flow unpredictability. You might gross $60,000 in a year but earn $15,000 of that in a single month and almost nothing in another. Fixed monthly premiums become a real burden during dry spells. Understanding this reality is the first step toward making smarter choices.
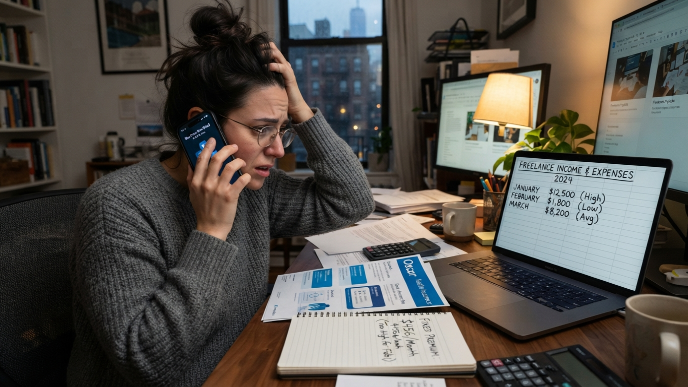
Figure Out What Insurance You Actually Need
Before you compare plans or prices, sit down and figure out which types of insurance genuinely apply to your life. Not every freelancer needs the same coverage, and buying things you don’t need is a fast way to drain money you can’t spare.
Here’s what most freelancers should consider:
- Health insurance (non-negotiable, one medical emergency can wipe you out)
- Professional liability or errors and omissions insurance
- Disability insurance (your ability to work IS your income)
- Business property insurance if you own expensive equipment
- Life insurance if anyone depends on your income
I skipped disability insurance for my first three years of freelancing. Then I sprained my wrist badly and couldn’t type for six weeks. Six weeks of zero income with bills still rolling in changed my perspective permanently.
Start with health coverage. Then add professional liability if clients require it or your work carries risk. Layer in disability and other policies as your income stabilizes.
Health Insurance Options That Actually Work on an Irregular Income
This is the big one. Health insurance feels like the hardest puzzle for freelancers, but you have more options than you probably think.
The ACA Marketplace
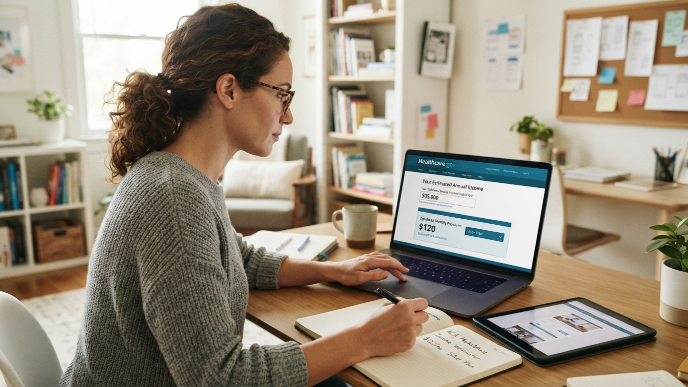
Healthcare.gov (or your state’s marketplace) is genuinely built for people like us. When you apply, you estimate your annual income, and the system calculates subsidies based on that number. If your income drops, you can update your estimate mid-year and get larger subsidies. If it rises, adjust upward so you don’t owe money at tax time.
I’ve used a Silver plan through the marketplace for three years now. During a slow year when I earned around $35,000, my monthly premium dropped to about $120 after subsidies. The key is updating your income estimate whenever things change significantly.
Freelancers Union and Group Plans
Organizations like the Freelancers Union offer group health plans in some states. The rates can be competitive because you’re pooling risk with thousands of other independent workers. Worth checking even if you’re skeptical.
Health Sharing Ministries
These aren’t technically insurance, and they come with restrictions (some exclude pre-existing conditions or require lifestyle agreements). But programs like Medishare or Christian Healthcare Ministries can cost significantly less per month. I used one briefly during a very lean year. Just read the fine print carefully.
A Simple Insurance Guide for Freelancers Without Steady Income: The Budget Method
Here’s the actual budgeting framework I use, and it’s the thing that finally made insurance manageable.
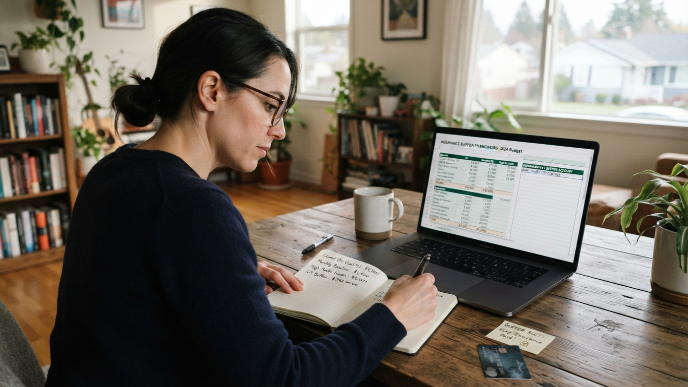
Instead of basing my insurance budget on monthly income, I calculate based on my lowest earning quarter from the previous year. That becomes my baseline. If my worst quarter brought in $4,500, I know I need insurance costs that I can cover on roughly $1,500 a month.
During high-earning months, I put 10% of everything over my baseline into a dedicated “insurance and taxes” savings account. This account acts as a buffer. When a slow month hits and premiums feel heavy, the buffer covers the gap.
I keep this account separate from my emergency fund. It has one job: keep my insurance paid no matter what. This approach removed the anxiety I used to feel every time a premium hit my checking account during a dry spell.
The trick is discipline during good months. When a $5,000 client payment lands, the temptation to spend freely is real. But that buffer account is what keeps your coverage intact when work slows down.
Professional Liability Insurance: Do You Really Need It?
Honestly, it depends on what you do. If you’re a freelance graphic designer making logos, your risk profile is very different from a freelance consultant giving business strategy advice that could cost a company millions if it goes wrong.
I’m a freelance writer and content strategist. A client once threatened legal action because they claimed my copy caused them to lose a partnership. Nothing came of it, but that week of stress convinced me to get an errors and omissions policy. I pay about $40 a month through Hiscox, and it covers up to $1 million in claims.
Professional liability insurance protects you when a client says your work caused them financial harm. If you do any of the following, seriously consider it:
- Consulting or advising businesses
- Creating content that makes factual claims
- Designing products or interfaces people rely on
- Managing money, accounts, or data for clients
If you’re a freelance pet photographer, you can probably skip it. Context matters.
Disability Insurance When Your Income Fluctuates
This is the coverage most freelancers ignore, and it’s arguably the most important after health insurance. Your ability to work is literally your entire business. If you can’t work, you earn nothing.
Traditional disability policies base benefits on your income history. For freelancers, insurers typically look at your last two to three years of tax returns and average them. If you’ve been freelancing for less than two years, some companies won’t cover you at all, but others like Guardian or Breeze are more flexible with newer freelancers.
Short-term disability policies are usually cheaper and cover you for three to six months. Long-term disability kicks in after that and can last years. I carry a short-term policy because statistically, most disabilities that affect freelancers (injuries, surgeries, mental health crises) resolve within a few months.
My monthly premium is around $65 and would replace about 60% of my average income if I couldn’t work. Not glamorous, but enough to keep the lights on.
How to Save Money on Premiums Without Gutting Your Coverage
Cutting costs is essential when income fluctuates, but dropping coverage entirely is dangerous. Here’s what actually works.
Choose higher deductible plans. If you’re generally healthy and don’t visit the doctor often, a high-deductible health plan (HDHP) paired with a Health Savings Account (HSA) can save you hundreds per month. I switched to an HDHP two years ago and cut my premium nearly in half. The HSA contributions are tax-deductible too, which helps at tax time.
Bundle policies when possible. Some insurers like Next Insurance or Hiscox offer discounts when you combine general liability with professional liability. I saved about 15% by bundling.
Pay annually if you can. Many insurers offer a discount (usually 5% to 10%) if you pay the full year upfront instead of monthly. During a strong earning period, I’ll prepay my liability policy for the year. One less bill to worry about during slow months.
Review your coverage every year. Your needs change. Maybe you dropped a service that carried more risk. Maybe you bought equipment that needs coverage. An annual review takes 30 minutes and can save real money.
Frequently Asked Questions
What’s the cheapest health insurance option for freelancers?
The ACA marketplace with income-based subsidies is usually the most affordable path. If your freelance income is modest, you might qualify for significant premium reductions. During my lowest earning year, subsidies brought my Silver plan premium under $130 a month. Always update your income estimate when things change so your subsidies stay accurate.
Can freelancers without steady income even get disability insurance?
Yes, though it takes a bit more effort. Insurers like Breeze and Guardian will underwrite freelancers based on tax return averages. You’ll typically need at least one to two years of filed returns. The benefit amount might be lower than a salaried employee would receive, but having something beats having nothing when you physically can’t work.
Is a simple insurance guide for freelancers without steady income really different from regular advice?
Absolutely. Standard advice assumes predictable paychecks and employer contributions. Freelancers deal with fluctuating income, self-employment taxes eating into their budget, and no employer subsidizing premiums. The budgeting strategies, plan types, and coverage priorities are genuinely different. What works for a salaried employee often backfires for someone whose income changes every month.
Do I need business insurance if I work from home?
It depends on your work. Your homeowner’s or renter’s policy probably won’t cover business equipment or client-related claims. If you own expensive gear like cameras, computers, or specialized tools, a small business property policy is smart. If clients visit your home or you store client data, general liability coverage becomes important too. Even a basic policy through Next Insurance can cost under $30 a month.
Should I get life insurance as a freelancer?
If someone depends on your income, yes. A simple term life policy is cheap when you’re younger, often $20 to $30 a month for a healthy person in their 30s. If you’re single with no dependents, it’s lower priority. Focus your budget on health, liability, and disability coverage first, then add life insurance when it makes financial sense.
Conclusion
Insurance as a freelancer doesn’t have to feel overwhelming or impossibly expensive. The real key is accepting that your approach has to match your reality, which means flexible budgeting, honest income estimates, and coverage that protects what matters most. What’s the one type of insurance you’ve been putting off that you know you probably need?