If you’ve ever stared at an insurance quote comparison screen at 11 PM, half asleep and completely overwhelmed, this low cost insurance guide for people short on time was written for you. I’ve been there. Three kids, two jobs, and zero patience for fine print. Finding affordable coverage shouldn’t require a weekend of research. You need a fast, honest path to a policy that protects your family without draining your bank account. That’s exactly what this is.
Why Most People Overpay for Insurance (And How to Stop)
Here’s something that bugged me for years: I was paying way too much simply because I never shopped around. Inertia is the insurance industry’s best friend. Companies count on you auto-renewing every year without questioning the premium.
The fix is embarrassingly simple. Set a calendar reminder 30 days before your renewal date. That one small habit saved me $640 on auto insurance last year. I spent maybe 45 minutes total getting three quotes through Policygenius and The Zebra, then called my existing provider and asked them to match the lowest one. They did, partially, and I switched for the rest.
You don’t need to become an insurance expert. You just need to stop being loyal to a company that isn’t being loyal to your wallet.
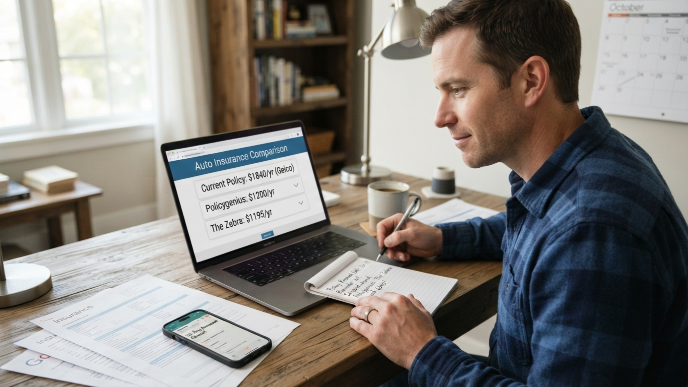
Figure Out What Coverage You Actually Need
Most people buy more coverage than necessary because they’re afraid of getting it wrong. That fear costs real money every single month.
Start with the basics. If you’re shopping for auto insurance, your state has minimum liability requirements. Those minimums are often genuinely too low, but you don’t need every add-on your agent suggests. Gap coverage on a paid-off car? Skip it. Rental reimbursement when you have a second vehicle at home? Probably unnecessary.
For health insurance, the same logic applies. If you’re generally healthy and under 40, a high-deductible health plan paired with an HSA through your employer can cut your monthly premium significantly. I switched to this setup two years ago and saved about $180 per month. The HSA contributions are tax-deductible too, which is a nice bonus come April.
A Quick Rule of Thumb
Insure against things that would financially wreck you. Don’t insure against inconveniences. A cracked phone screen is annoying. A house fire is catastrophic. Spend your premium dollars accordingly.
The Fastest Way to Compare Quotes Without Losing Your Mind
Comparison sites exist for a reason, and they’re a massive time saver for anyone following a low cost insurance guide for people short on time. But not all of them work the same way.
Policygenius is my go-to for life and renters insurance. You fill out one form, get multiple quotes, and an actual human advisor follows up if you want help. The Zebra and Jerry work well for auto insurance. Insurify is another solid option that pulls quotes in under two minutes.
One thing I learned the hard way: don’t use more than two or three comparison sites for the same type of insurance. Each one triggers a soft or hard inquiry depending on the insurer, and you’ll get flooded with calls and emails. Pick one or two, compare, decide, and move on. The goal here is speed without sacrifice.
Bundle Your Policies and Save Real Money
Bundling isn’t just marketing fluff. Combining your auto and home or renters insurance with one carrier genuinely drops your total cost. I bundle through State Farm right now and the multi-policy discount knocks about 15% off both premiums.
Most major carriers offer bundling: Progressive, Allstate, GEICO, Nationwide. The discount typically ranges from 5% to 25% depending on the company and the combination of policies. Even if you’re renting, pairing a cheap renters policy (often under $15/month) with your auto insurance can trigger a bundle discount that more than covers the renters premium.
Call your current provider and ask what bundling options they have. This takes about ten minutes and could save you hundreds annually. If they can’t beat a competitor’s bundle, switch. Loyalty doesn’t pay your bills.
Raise Your Deductibles Strategically
This one makes people nervous, but hear me out. Raising your auto insurance deductible from $250 to $1,000 can lower your premium by 20% to 40%. That’s potentially $300 to $500 back in your pocket every year.
The catch is obvious: you need to be able to cover that $1,000 if something happens. So before you raise anything, make sure you have at least that amount sitting in an emergency fund. If you don’t, build it first.
I raised my deductibles on both auto and homeowners insurance about three years ago. I’ve filed zero claims since then. The math has worked heavily in my favor. For most people who drive carefully and maintain their home, higher deductibles are one of the smartest moves in any low cost insurance guide.
Ask About Discounts You Didn’t Know Existed
Insurance companies have discounts for everything, and they rarely volunteer them. You have to ask.
Here are some that surprised me:
- Paperless billing discount (usually 3% to 5%)
- Good student discount for kids on your auto policy
- Defensive driving course completion
- Professional association or alumni group membership
- Low mileage discount if you work from home
- Home security system discount on homeowners insurance
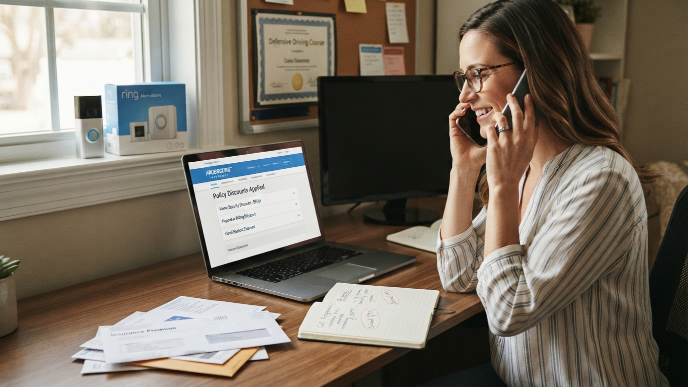
When I called Progressive last year, I mentioned that I’d installed a Ring doorbell and deadbolt sensors. They applied a home security discount I never would have received if I hadn’t brought it up. Five minutes on the phone saved me $90 for the year.
Use Technology to Speed Up the Process
If you’re short on time, your phone can do most of the heavy lifting. Apps like Jerry for auto insurance literally renegotiate your policy or find a cheaper one while you go about your day. You give the app permission, it pulls your current policy details, shops around, and presents better options.
Lemonade handles renters and homeowners insurance almost entirely through their app. I got a renters policy through them in under 90 seconds once. Not exaggerating. The AI-driven claims process is fast too, though I’ve only tested it once for a stolen bike.
For health insurance, if you’re buying on the marketplace, HealthSherpa is faster and cleaner than the official Healthcare.gov site. Same plans, same subsidies, better user experience. IMO it should be the default.
Don’t Skip Life Insurance Just Because It Feels Overwhelming
A lot of people put off life insurance because the process feels complicated and time-consuming. It doesn’t have to be. Term life insurance is straightforward and cheap, especially if you’re under 45 and reasonably healthy.
I got a 20-year, $500,000 term policy through Haven Life (a MassMutual subsidiary) for about $28 per month. The entire application took 20 minutes online, no medical exam required. Ladder and Bestow offer similar no-exam term policies with comparable pricing.
If anyone depends on your income, you need life insurance. Period. A low cost insurance guide for people short on time wouldn’t be complete without saying that bluntly. The process is faster and cheaper than most people assume, and putting it off is the most expensive mistake you can make.
Review Your Policies Once a Year, No More
You don’t need to obsess over insurance. But ignoring it entirely is how you end up overpaying for years. Once a year, ideally a month before renewal, spend 30 to 45 minutes doing a quick check.
Pull up your current declarations page. Compare your coverage and premium to two or three fresh quotes. Check for new discounts. Make sure your coverage still matches your life situation. Had a kid? You might need more life insurance. Paid off your car? You might be able to drop collision coverage.
That’s it. One focused session per year keeps your costs low and your coverage right. Put it on your calendar like a dentist appointment. Except this one actually saves you money.
Frequently Asked Questions
What’s the fastest way to get a cheap insurance quote?
Use a comparison site like Policygenius, The Zebra, or Jerry. You enter your info once and get multiple quotes in minutes. I’ve personally gotten usable auto quotes in under three minutes through Jerry. Skip calling individual agents unless you want to negotiate a specific price match afterward.
Can I trust online-only insurance companies?
Yes, most of them. Companies like Lemonade, Bestow, and Haven Life are backed by major underwriters and rated by AM Best. I’ve had policies with Lemonade and Haven Life and both handled everything smoothly. Just check the financial strength rating before you buy, and you’ll be fine.
Is bundling always cheaper than buying separate policies?
Usually, but not always. Sometimes a smaller carrier offers a standalone auto rate so low that even without a bundle discount, it beats the bundled price from a big-name company. Always compare the total cost of bundled versus separate before committing. I’ve seen it go both ways.
How much life insurance do I actually need?
A common starting point is 10 to 12 times your annual income. If you earn $60,000, aim for $600,000 to $720,000 in coverage. Factor in debts, childcare costs, and your partner’s income too. Term life is almost always the right choice unless you have a very specific estate planning need.
Does a low cost insurance guide work for self-employed people?
Absolutely. Self-employed folks often save even more because they’re starting from a higher baseline. Health insurance through the ACA marketplace with income-based subsidies, bundled business and auto policies, and term life through no-exam providers all work perfectly for freelancers and small business owners.
Conclusion
Finding affordable insurance doesn’t require hours of research or an advanced degree in fine print. A few smart moves, done once a year, keep your coverage solid and your costs low. What’s the one insurance bill you’ve been meaning to tackle but keep putting off?