If you’ve ever had an insurer side-eye your EpiPen prescription or deny coverage for allergy testing, you already know why a foolproof insurance guide for people with severe allergies matters so much. I spent three years fighting with my health plan after my tree nut allergy landed me in the ER twice. The bills were brutal. The confusion was worse. Nobody handed me a roadmap, so I built one myself, and I’m sharing it here because you shouldn’t have to figure this out mid-anaphylaxis.
Why Standard Health Insurance Falls Short for Allergy Sufferers
Most health insurance plans treat allergies like a minor inconvenience. A little Claritin, maybe a copay for an allergist visit, done. But when your allergies involve anaphylaxis risk, immunotherapy, or specialty medications, those “standard” plans suddenly have gaping holes.
I found this out when my insurer classified my sublingual immunotherapy as “experimental” and refused to pay. Meanwhile, my allergist had been prescribing it for years with solid clinical evidence behind it. The problem isn’t that insurance companies are evil. The problem is that their default coverage tiers weren’t designed with severe allergy patients in mind.
You need a plan that covers emergency room visits without punishing you with massive out-of-network charges. You need prescription coverage that actually includes epinephrine auto-injectors at a reasonable cost. And you need a policy that recognizes allergist and immunologist visits as essential, not optional. If your current plan doesn’t check those boxes, you’re exposed in ways that could cost you thousands.
Step 1: Know Exactly What Your Allergies Require Medically
Before you even look at an insurance policy, sit down and map out every medical need tied to your allergies. I’m talking specifics. Not “I have a peanut allergy” but “I need two EpiPen two-packs per year, quarterly allergist visits, annual blood panels for IgE levels, and I may need emergency care at any point.”
Write it all down. Include medications, devices, specialist visits, lab work, and any immunotherapy you’re considering. This list becomes your shopping checklist when comparing plans.
Here’s something I wish someone had told me earlier: ask your allergist to write a letter of medical necessity for each item on your list. That single document has saved me from three separate claim denials. Insurers respond differently when a board-certified specialist puts their reasoning in writing.
Step 2: Compare Plans Using Your Actual Allergy Costs
Forget the monthly premium for a second. The cheapest plan per month almost always costs more over the year when you have severe allergies. I learned this the hard way with a high-deductible plan that looked affordable until I hit the pharmacy counter.
Pull up the formulary for every plan you’re considering. A formulary is the list of drugs a plan covers and at what tier. Search for your specific medications. EpiPen, Auvi-Q, epinephrine generic auto-injectors, antihistamines, corticosteroids, whatever you use. If your epinephrine device sits on Tier 3 or higher, your copay could be $200 or more per fill.
Then check the plan’s specialist copay or coinsurance. Some HMO plans require referrals every single time you see your allergist, which adds friction and delays. PPO plans cost more monthly but let you see specialists directly. For someone whose throat could close up from a stray cashew, that direct access matters.
Run the Real Numbers
Add up your estimated annual costs under each plan: premiums, deductible, copays for specialist visits, prescription costs, and potential ER visits. I use a simple spreadsheet. The plan that “wins” is rarely the one with the lowest premium. It’s the one with the lowest total annual cost based on your actual usage.
Step 3: Understand Emergency Coverage Inside and Out
This one’s personal. My first ER visit for anaphylaxis happened while I was traveling two states away. My insurer covered the visit, but at out-of-network rates, which meant I owed $4,200 after insurance “paid their share.” That bill sat on my credit report for months.
Since then, I’ve made emergency coverage my number one filter when choosing a plan. Here’s what to look for:
- Does the plan cover out-of-network emergency rooms at in-network rates?
- Is there a separate ER copay, and if so, is it waived if you’re admitted?
- Does the plan cover ambulance transport, and at what percentage?
- Are urgent care visits covered as an alternative for less severe reactions?
The No Surprises Act, which went into effect in January 2022, helps protect you from surprise bills for emergency services. But it doesn’t cover every scenario, and state-level protections vary. Read your plan’s Summary of Benefits and Coverage document. It’s dry reading, but it’s the only document that tells you the truth about what you’ll actually pay.
Step 4: Fight for Prescription Coverage That Actually Works
Epinephrine is the single most important medication for anyone with severe allergies, and it’s also one of the most frustrating to get covered well. Brand-name EpiPen two-packs can run over $650 without insurance. Generics from Mylan and Teva brought costs down, but your plan still might stick them on a high copay tier.
Here’s what’s worked for me. First, always check if your plan offers a preferred alternative. Some insurers favor Auvi-Q or generic epinephrine over brand-name EpiPen. Second, use manufacturer coupons and patient assistance programs alongside your insurance. Kaléo, the maker of Auvi-Q, has a program that can bring your cost to zero if you have commercial insurance. Mylan offers savings cards for EpiPen as well.
If your plan denies or restricts a medication you need, file a formulary exception request. Your allergist submits a letter explaining why you need that specific drug, and the insurer reviews it. I’ve won two of these appeals. They take about two to four weeks, and they’re absolutely worth the effort.
Step 5: Build Your Foolproof Insurance Guide for People With Severe Allergies Around the Right Plan Type
Choosing between an HMO, PPO, EPO, or high-deductible health plan (HDHP) with an HSA isn’t just a financial decision when you have severe allergies. It’s a safety decision.
PPO plans give you the most flexibility. You can see any allergist or immunologist without a referral, and you get some coverage even if you go out of network. For people who travel often or live in areas with limited allergy specialists, a PPO is usually the safest bet.
HMO plans cost less but lock you into a network and require referrals. If your preferred allergist is in-network and you rarely travel, an HMO can work. Just make sure your network includes a hospital with an allergy and immunology department.
HDHPs with HSAs sound appealing because of the tax-advantaged savings account. But here’s the catch: you pay everything out of pocket until you hit a deductible that’s often $1,500 or more for an individual. If you fill epinephrine prescriptions multiple times a year and see an allergist quarterly, you could blow through that deductible fast, with no copay relief along the way.
IMO, the sweet spot for most severe allergy patients is a mid-tier PPO with a moderate deductible and strong prescription coverage. It’s not the cheapest monthly payment, but it protects you when things go sideways.
Step 6: Don’t Overlook Supplemental and Specialty Coverage
Your primary health plan might not cover everything you need. That’s where supplemental options come in, and most people with allergies never even consider them.
Accident and critical illness policies from companies like Aflac or Colonial Life can provide a cash payout if you’re hospitalized for anaphylaxis. That money goes directly to you, not the hospital, so you can use it to cover deductibles, lost wages, or whatever you need. These policies typically cost $20 to $50 per month and don’t require medical underwriting that would flag your allergy history.
If you travel frequently, a travel medical insurance policy is non-negotiable. Companies like World Nomads and Allianz offer plans that cover emergency treatment abroad, including anaphylaxis. I buy one every time I leave the country. It’s cheap peace of mind.
Also look into whether your state Medicaid program or the ACA marketplace offers enhanced benefits for chronic conditions. Some state marketplace plans include allergy-specific care management programs that cover extra visits, testing, and even nutritional counseling for food allergy management.
Step 7: Document Everything and Appeal Every Denial
Insurance companies count on you giving up. I mean that sincerely. The denial letter is designed to feel final, but it almost never is.
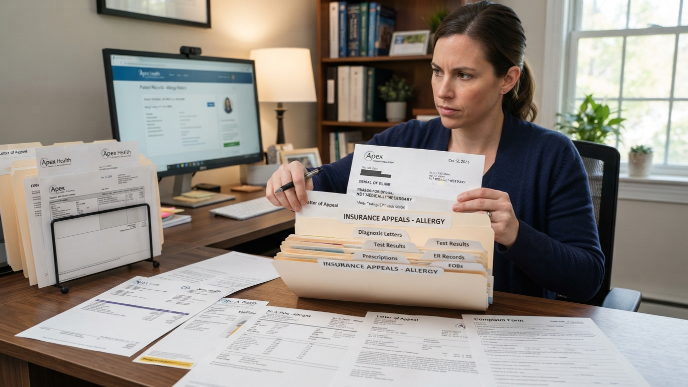
Keep a file, digital or physical, with every piece of allergy-related medical documentation you have. Diagnosis letters, test results, prescription records, ER discharge summaries, and every single Explanation of Benefits statement your insurer sends. When a claim gets denied, you pull from this file to build your appeal.
The first level of appeal is an internal review by your insurer. If that fails, you have the right to an external review by an independent third party. According to data from the Kaiser Family Foundation, roughly 40% to 60% of external appeals for medical necessity are decided in the patient’s favor. Those odds are good enough to always try.
FYI, your state’s Department of Insurance can also intervene if you believe your insurer is acting in bad faith. I filed a complaint with mine after a particularly absurd denial for allergy testing, and the insurer reversed their decision within two weeks.
Frequently Asked Questions
Does health insurance cover allergy testing?
Most health insurance plans cover allergy testing when an in-network allergist orders it and documents medical necessity. Skin prick tests and blood panels for specific IgE are commonly covered. Some plans require prior authorization, so always call your insurer before the appointment to confirm coverage and avoid surprise bills.
Can an insurer deny coverage because of severe allergies?
Under the Affordable Care Act, insurers cannot deny you coverage or charge higher premiums because of pre-existing conditions, including severe allergies. This applies to all ACA marketplace plans and employer-sponsored group plans. Short-term health plans, however, can still exclude pre-existing conditions, so avoid those if possible.
How do I get my EpiPen covered at a lower cost?
Check your plan’s formulary to see if a generic or preferred alternative costs less. Use manufacturer savings programs like the Kaléo Auvi-Q copay card or Mylan’s EpiPen savings offer. If your plan places epinephrine on a high tier, ask your allergist to submit a formulary exception request with a medical necessity letter.
What type of insurance plan is best for someone with severe allergies?
A mid-tier PPO plan with moderate deductibles and strong prescription drug coverage tends to work best for severe allergy patients. It gives you direct access to specialists and broader network options for emergencies. High-deductible plans can leave you paying thousands before coverage kicks in, which is risky when you need frequent prescriptions and specialist care.
Should I buy travel insurance if I have life-threatening allergies?
Absolutely. Your domestic health plan likely won’t cover emergency treatment outside the country, and even domestic travel can put you out of network. Companies like World Nomads and Allianz sell travel medical policies that cover anaphylaxis emergencies abroad. Read the fine print to confirm they don’t exclude allergic reactions as a pre-existing condition.
Conclusion
Getting the right insurance when you live with severe allergies takes effort upfront, but it saves you from financial chaos and dangerous gaps in care down the line. Your allergies aren’t a footnote in your health, so your coverage shouldn’t treat them like one. What’s been your biggest frustration dealing with insurance and allergy coverage?