If you’ve ever stared at a medical bill wondering how you’re supposed to afford insurance on 25 hours a week, this easy insurance guide for part time hourly workers is the one I wish I’d had three years ago. I spent months uninsured while working two part time jobs because I assumed I didn’t qualify for anything. Turns out, I was wrong. Really wrong. And I left money on the table because nobody told me what was actually available.
Why Part Time Workers Get Left Out of the Insurance Conversation
Most insurance advice online is written for full time salaried employees who get benefits handed to them during onboarding. That’s not your reality. When you’re clocking in for 20 to 30 hours a week at an hourly rate, your employer probably isn’t required to offer you health coverage. Under the Affordable Care Act, companies only need to provide insurance to employees who average 30 or more hours per week. So if you’re sitting at 28 hours, you’re technically on your own.
That doesn’t mean you’re out of options. It just means you have to go find them yourself, which is annoying but absolutely doable. The biggest mistake I made was assuming that “no employer coverage” meant “no affordable coverage.” That’s just not true anymore, and the sooner you realize it, the better off your bank account will be.
Step One: Figure Out What You Actually Need
Before you start shopping for plans, sit down and think honestly about what kind of coverage you need right now. Not what would be nice to have someday. What you actually need.
Are you generally healthy and just want protection against a catastrophic accident or illness? A high-deductible plan might work perfectly. Do you take prescription medications regularly? Then you need a plan with decent drug coverage, and you should check formularies before signing up. I learned that the hard way when my first Marketplace plan didn’t cover a medication I’d been taking for years.
Write down three things: any current prescriptions, any doctors you want to keep seeing, and how much you can realistically spend each month. That list becomes your shopping filter. Everything that doesn’t match gets tossed.
Step Two: Check If Your Employer Offers Anything at All
Some employers actually do offer benefits to part time workers, even if they’re not legally required to do so. Starbucks, for example, extends health insurance to employees working as few as 20 hours per week. Costco, UPS, and REI have similar programs. If you work for a larger company, ask your HR department directly. Don’t just assume the answer is no.
Even if your employer doesn’t offer full medical coverage, they might provide access to a dental plan, vision coverage, or a voluntary accident policy. These smaller benefits can fill gaps you didn’t even know you had. I once worked at a retail chain that offered a basic accident policy for $11 a month. It paid out $500 when I broke my wrist skateboarding. Not life-changing money, but it covered my ER copay and then some.
Step Three: Head to the Health Insurance Marketplace
The ACA Marketplace at HealthCare.gov (or your state’s exchange if you live in a state that runs its own) is where most part time hourly workers end up finding real coverage. Open enrollment typically runs from November 1 through January 15, but you can qualify for a Special Enrollment Period if you’ve had a qualifying life event like losing other coverage, moving, or getting married.
Here’s the part that matters most: subsidies. If your income falls between 100% and 400% of the federal poverty level, you likely qualify for premium tax credits that lower your monthly cost. For a single person in 2024, that’s roughly between $15,060 and $60,240. Many part time workers fall right in that range. When I applied for the first time, my monthly premium dropped from $340 to $87 because of the subsidy. I almost didn’t apply because I thought I made “too much.” I didn’t.
Use the Marketplace’s income estimator tool before you start browsing plans. It takes five minutes and gives you a realistic picture of what you’ll actually pay.
Step Four: Look Into Medicaid (Seriously)
If your part time income is low enough, you might qualify for Medicaid, which covers you at little to no cost. In the 40 states (plus Washington D.C.) that expanded Medicaid under the ACA, adults earning up to 138% of the federal poverty level qualify. For a single person in 2024, that’s about $20,783 per year.
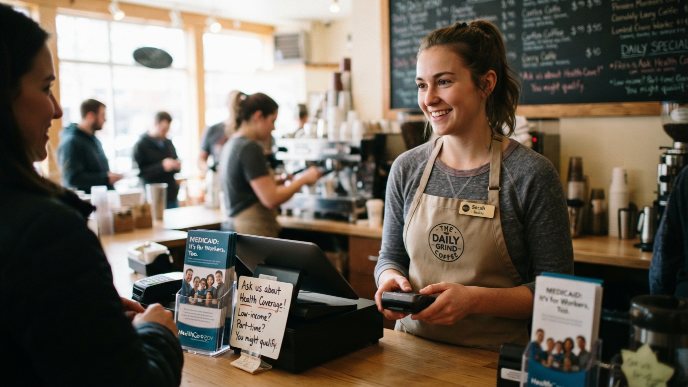
A lot of part time workers skip Medicaid because they think it’s only for people who aren’t working. That’s a myth. Medicaid doesn’t care whether you work 10 hours or 40 hours. It looks at your income, period. I had a coworker at a coffee shop who qualified for Medicaid while working 25 hours a week and had zero monthly premiums. She’d been paying out of pocket for urgent care visits for two years before she found out.
You can apply through HealthCare.gov or directly through your state’s Medicaid office. The application usually takes about 20 minutes, and many states process approvals within a few weeks.
Step Five: Consider Short Term Health Insurance as a Bridge
If you’re between jobs, waiting for open enrollment, or just need something temporary, short term health insurance can fill the gap. These plans are cheaper, often $100 to $200 a month, and you can usually get approved within a day or two.
But here’s the honest trade-off: short term plans don’t have to follow ACA rules. That means they can deny coverage for pre-existing conditions, they often don’t cover prescriptions or mental health, and they have annual or lifetime caps. Companies like Pivot Health and United Healthcare offer popular short term options, but read the fine print carefully.
I used a short term plan for four months once while transitioning between part time gigs. It gave me peace of mind for emergencies, but I wouldn’t rely on it as a long term solution. Think of it as a parachute, not a house.
Easy Insurance Guide for Part Time Hourly Workers: Understanding Plan Types
You’ll run into four main plan types when shopping, and knowing the difference saves you from picking the wrong one.
HMO (Health Maintenance Organization)
HMO plans are usually the cheapest monthly premium option. You pick a primary care doctor, and you need referrals to see specialists. You also have to stay in-network for everything except true emergencies. If you’re on a tight budget and don’t mind working within a network, HMOs can be great.
PPO (Preferred Provider Organization)
PPO plans cost more per month but give you way more flexibility. You can see any doctor without a referral, and out-of-network care is still partially covered. If you see multiple specialists or travel frequently between jobs, PPOs make life easier.
EPO and POS Plans
EPO plans work like PPOs but don’t cover out-of-network care at all. POS plans blend HMO and PPO features. Both are less common on the Marketplace but worth understanding if you see them listed.
Pick based on how you actually use healthcare, not based on which acronym sounds fanciest. I chose a PPO my first year because it sounded “better” and ended up paying $60 more per month for flexibility I never used.
Step Six: Don’t Forget Dental and Vision
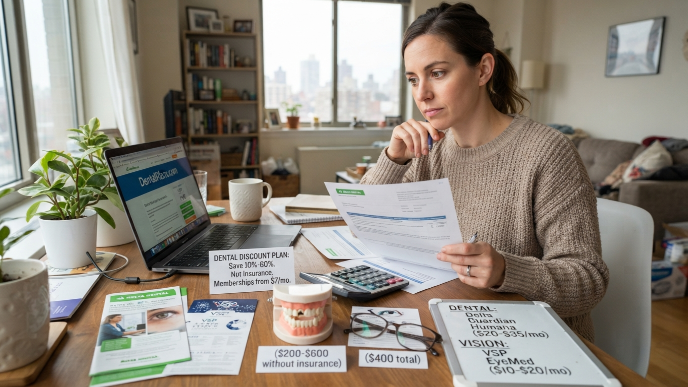
Medical insurance gets all the attention, but dental and vision coverage matter too, especially when you’re on a tight budget. A single cavity filling can run $200 to $600 without insurance. An eye exam plus glasses can easily hit $400.
The Marketplace offers standalone dental plans, and companies like Delta Dental, Guardian, and Humana sell affordable individual plans directly. For vision, VSP and EyeMed are the two biggest names. Monthly premiums for basic dental plans start around $20 to $35, and vision plans run about $10 to $20.
If you’re really pinching pennies, dental discount plans (not insurance, but a membership that gives you reduced rates) from companies like DentalPlans.com can cut costs by 10% to 60% at participating dentists. I used one for a year and saved about $180 on a cleaning and a filling. Not glamorous, but practical.
Step Seven: Use Free and Low Cost Resources While You Sort Things Out
Even after you pick a plan, you might have gaps. Here’s what helped me during the months I was still figuring things out.
Community health centers funded by the federal government offer primary care on a sliding fee scale based on your income. You can find one near you at FindAHealthCenter.hrsa.gov. I got a full physical and blood work done for $35 at one in Austin.
GoodRx and RxSaver can slash prescription drug prices at major pharmacies, sometimes by 80% or more, even without insurance. Telehealth apps like GoodRx Care and Sesame offer doctor visits starting at $20 to $50.
These aren’t replacements for real insurance, but they keep you healthy and solvent while you get a plan in place.
Common Mistakes Part Time Workers Make with Insurance
A few pitfalls trip up part time hourly workers over and over again. I’ve made most of them personally, so consider this your cheat sheet.
Not reporting income changes to the Marketplace is a big one. If your hours increase or you pick up a second job, your subsidy amount might change. If you don’t update your application, you could owe money back at tax time. I got hit with a $400 surprise one April because I didn’t report extra holiday hours.
Another mistake is choosing the cheapest plan without reading the benefits summary. A $50 monthly premium sounds amazing until you realize the deductible is $8,000 and nothing is covered until you hit it.
Finally, missing open enrollment and assuming you’re stuck for the whole year. Check if you qualify for a Special Enrollment Period. Job changes, income drops, and losing other coverage all count as qualifying events.
Frequently Asked Questions
Can part time hourly workers get health insurance through the Marketplace?
Yes, absolutely. The ACA Marketplace doesn’t have a minimum hours requirement. If you’re a legal U.S. resident and your employer doesn’t offer affordable coverage, you can shop for plans on HealthCare.gov. Many part time workers qualify for subsidies that bring monthly premiums down significantly based on their annual income.
How much does insurance cost for someone working part time?
It depends on your income, location, and the plan you choose. With premium tax credits, many part time workers pay between $50 and $150 per month for a Marketplace plan. Without subsidies, unsubsidized plans can run $300 to $500 or more. Always check your subsidy eligibility before assuming you can’t afford it.
Is there a simple insurance guide for part time hourly workers who’ve never had coverage?
You’re reading it. Start by checking Medicaid eligibility, then head to HealthCare.gov during open enrollment. Use the income estimator, compare two or three plans that fit your prescriptions and doctors, and pick one. It doesn’t have to be perfect. Having any coverage beats having none.
What happens if I work two part time jobs but neither offers insurance?
You shop for your own plan through the Marketplace. Combine your estimated income from both jobs when you apply, because that total determines your subsidy. Neither employer is obligated to cover you if you’re under 30 hours at each, but your combined income might still qualify you for significant financial help.
Can I get dental and vision insurance separately from medical?
Yes. The Marketplace offers standalone dental plans, and you can buy vision plans directly from companies like VSP or EyeMed. You don’t need to bundle them with a medical plan. Monthly costs are usually pretty low, around $20 to $35 for dental and $10 to $20 for vision.
Conclusion
Getting insured as a part time hourly worker isn’t as complicated as it feels when you’re starting from zero. The options are real, the subsidies are often bigger than you’d expect, and the peace of mind is worth every minute you spend on the application. So, have you checked your Marketplace eligibility yet?