If you need a top insurance guide for one day decision makers, you already know the pressure. Maybe your lease starts tomorrow, your car purchase closes this afternoon, or your employer needs proof of coverage by end of business. You don’t have the luxury of weeks of research. You need clarity right now, and you need it without making a costly mistake. I’ve been in that exact seat more times than I’d like to admit, and I’ve learned some hard lessons along the way.
Why One Day Insurance Decisions Feel So Overwhelming
Insurance is one of those purchases where the stakes feel invisible until they aren’t. You’re paying for something you hope you never use, which makes it psychologically painful to rush. When you compress the entire buying process into a single day, your brain floods with doubt.
Here’s what actually happens: you open three or four websites, get hit with jargon like “aggregate limits” and “loss payee,” and suddenly you’re paralyzed. I remember buying renter’s insurance in four hours because my landlord literally wouldn’t hand over keys without it. I picked the first policy that seemed reasonable and later realized I was paying $30 more per month than I needed to. That’s real money over a year.
The trick isn’t to eliminate pressure. It’s to have a framework so the pressure doesn’t make you sloppy.
Step 1: Know Exactly What Type of Coverage You Need Before You Start Shopping
This sounds obvious, but most people skip it. They start Googling “best insurance” without first answering one critical question: what specific risk am I covering?
Auto insurance is different from renter’s insurance is different from short-term health coverage is different from event liability. Each has its own requirements, minimums, and common pitfalls. If you’re buying car insurance because you just purchased a vehicle, your state has mandatory minimum liability amounts. If you’re getting renter’s insurance for a new apartment, your landlord might require a specific coverage amount for personal property.
Before you open a single quote tool, write down three things: the type of insurance required, the minimum coverage amount mandated by whoever is asking for it, and your actual budget. That takes five minutes and saves you from wasting two hours comparing policies that don’t even fit your situation.
Step 2: Use Comparison Platforms Instead of Going Carrier by Carrier
Going directly to Geico, then State Farm, then Progressive, then Allstate individually will eat your entire day. Each site asks for the same information, each quote takes 10 to 15 minutes, and by the fourth one you’re mentally checked out.
Instead, use aggregator platforms. Policygenius works well for life and renter’s insurance. The Zebra and Jerry are solid for auto insurance comparisons. These tools pull multiple quotes at once, so you see pricing side by side without re-entering your details six times.
I used The Zebra last year when I needed to switch auto carriers in a single afternoon. It pulled quotes from nine carriers in about eight minutes. Were all nine quotes perfect? No. But it narrowed my options to three realistic choices fast enough that I could actually compare them thoughtfully.
One caveat: aggregators don’t always include every carrier. Some insurers like USAA or Erie only sell direct. If you know you qualify for a niche carrier, check their site separately.
A Top Insurance Guide for One Day Decision Makers Starts with Knowing Your Non-Negotiables
When you only have hours, you cannot compare every feature of every policy. You need to pick two or three factors that matter most and filter ruthlessly.
For most people making same-day decisions, these three filters work:
- Monthly premium (what fits your actual budget, not what feels cheap)
- Deductible amount (how much you’d pay out of pocket before coverage kicks in)
- Coverage limits (does it meet the minimum required by your landlord, lender, or state)
Everything else, roadside assistance, identity theft add-ons, equipment breakdown coverage, is secondary. You can always add riders or adjust coverage later. Right now, you need a policy that meets your requirements and doesn’t wreck your finances. That’s it.
I’ve watched friends spend three hours agonizing over whether to add umbrella coverage to a renter’s policy they needed that day. You can revisit that decision next week. Get the core coverage locked in first.
Step 3: Read the Declarations Page, Not the Marketing Copy
Insurance company websites are designed to sell you feelings. Peace of mind. Protection for what matters most. Warm stock photos of families laughing near golden retrievers. None of that tells you what your policy actually covers.
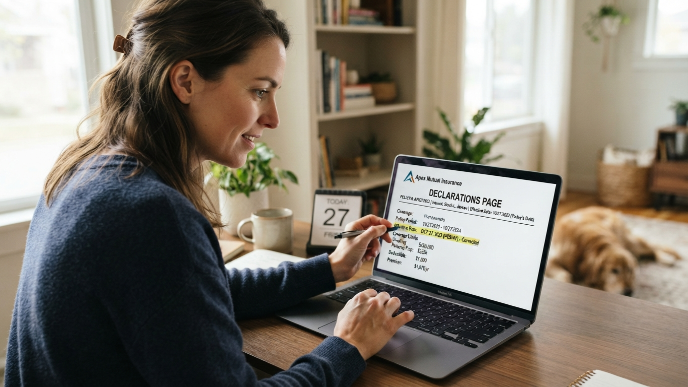
The declarations page, sometimes called the “dec page,” is the one-page summary that shows your coverage types, limits, deductibles, and premium. Every policy has one. Before you click “purchase,” make sure you’ve seen it or at least a preview of it.
Here’s what to check on the dec page:
- Your name and address are correct
- Coverage limits match what’s required
- The deductible is what you agreed to
- The effective date is today or whenever you need it to start
I once bought a policy where the effective date defaulted to the following Monday. I needed coverage that same Friday. Caught it only because I actually read the dec page before paying. A small detail like that can leave you completely unprotected during the gap.
Step 4: Don’t Ignore the Claims Process
This is the part most one day decision makers skip entirely, and I get it. When you’re rushing, the last thing you want to think about is filing a claim. But a cheap policy from a carrier with a nightmare claims process is worse than paying $15 more per month for a company that actually picks up the phone.
Before you finalize, spend five minutes doing one thing: search “[insurance company name] claims reviews” on Reddit or Google. You’ll find real experiences fast. Companies like Lemonade have a reputation for quick digital claims. Others, particularly some smaller regional carriers, have horror stories about delayed payouts and denied claims.
You don’t need to read 50 reviews. Skim 10. If you see a pattern of complaints about the same issue, that’s a red flag. If reviews are mostly positive with normal occasional gripes, you’re probably fine.
Step 5: Buy the Policy and Get Proof of Coverage Immediately
Once you’ve picked your policy, buy it online if possible. Most major carriers, including Progressive, Lemonade, State Farm, and Geico, let you purchase and get your proof of insurance digitally within minutes.
For auto insurance, you’ll get a digital ID card. Download it to your phone and also email it to yourself. For renter’s insurance, you’ll typically get a certificate of insurance you can forward directly to your landlord. For event or liability insurance, companies like Thimble or NEXT Insurance can issue same-day certificates.
Here’s a tip from personal experience: always save a PDF copy somewhere accessible, not just in your email inbox buried under 200 other messages. I keep mine in a dedicated folder on Google Drive. When my landlord randomly asked for updated proof of coverage eight months later, I had it in 30 seconds. That small habit saved me from scrambling.
Common Mistakes That One Day Insurance Buyers Make
Rushing creates specific, predictable errors. Knowing them in advance helps you sidestep them even under time pressure.
Choosing the lowest premium without checking the deductible. A $40/month auto policy with a $2,500 deductible means you’re paying $2,500 out of pocket for any claim before insurance covers a dime. For many people, a $1,000 deductible at $55/month makes way more financial sense.
Forgetting to ask about bundling is another one. If you already have auto insurance and you’re adding renter’s insurance, the same carrier often gives you a multi-policy discount. Even in a rush, one phone call or chat message can save you 10 to 15 percent.
Finally, not setting a calendar reminder to review the policy in 30 days. Your one day decision doesn’t have to be your forever decision. Most policies let you adjust coverage, change deductibles, or even switch carriers without penalty after the initial period. Give yourself permission to revisit it when you’re not under the gun.
Frequently Asked Questions
Can I actually get insurance coverage within one day?
Yes, absolutely. Most major carriers like Geico, Progressive, Lemonade, and State Farm offer instant or same-day coverage when you purchase online. Auto and renter’s policies are especially fast. Some specialty coverages, like commercial liability, might take slightly longer depending on the underwriting process, but many still issue same-day.
What should I prioritize when I only have a few hours to choose a policy?
Focus on three things: does it meet the minimum coverage required by your state, landlord, or lender? Is the monthly premium within your budget? And is the deductible an amount you could actually afford to pay if something happened? Everything else can wait until you have time to review and adjust.
Is it a bad idea to buy insurance without talking to an agent?
Not necessarily. Online purchasing works great for straightforward policies like auto, renter’s, or basic life insurance. If your situation is more complex, like insuring a business, a rental property, or high-value assets, a quick call with an independent agent can save you from buying the wrong coverage type entirely.
How does this top insurance guide for one day decision makers apply to health insurance?
Health insurance is trickier for same-day purchases because open enrollment periods and qualifying life events control when you can buy. If you’ve had a qualifying event like losing employer coverage or moving states, you typically have 60 days to enroll. Platforms like Healthcare.gov or eHealth can help you compare options quickly within that window.
Can I change my policy after I buy it the same day?
Most policies allow changes after purchase. You can adjust coverage limits, swap deductible amounts, or add riders. Some changes take effect immediately and others at your next billing cycle. If you realize you need to switch carriers entirely, you can usually cancel within the first 30 days without penalty, though you should confirm the specific cancellation terms with your carrier.
Conclusion
Buying insurance in a single day isn’t ideal, but it’s completely doable when you know what to focus on and what to ignore. The framework here has saved me real money and real stress across multiple last-minute purchases. What’s the tightest timeline you’ve ever had to lock in a policy?