When I first started looking for a top rated insurance guide for people on a fixed income, every result felt like it was written by someone who had never actually stressed over a premium payment. I know what it feels like to watch a bill eat into grocery money. Living on Social Security, a pension, or disability checks means every dollar has a job. The wrong insurance policy can wreck a carefully balanced budget in one billing cycle. The right one can save you from financial disaster without the monthly panic.
Why Insurance Feels So Complicated on a Fixed Budget
Most insurance content assumes you have flexibility. You don’t. When your income stays the same month after month, a $50 premium increase isn’t a minor annoyance. It’s a crisis. I’ve been there, staring at a renewal notice and doing mental math against my electric bill.
The insurance industry wasn’t built with fixed-income households in mind. Policies come bundled with features you’ll never use, and stripping them out takes effort most people don’t realize is even possible. But here’s the thing: you absolutely can find affordable, solid coverage. You just need to know where to look and what to ask for. That’s what this guide is really about, giving you the specific steps I wish someone had handed me five years ago.
Step 1: Figure Out What You Actually Need to Insure
Before you compare a single quote, sit down and list what genuinely needs coverage. Most people on a fixed income over-insure in some areas and dangerously under-insure in others.
Health insurance is non-negotiable. So is some form of liability protection if you own or rent a home. But do you really need that extended warranty plan on your appliances? Probably not. Do you need a life insurance policy if no one depends on your income? Maybe not either.
I spent two years paying for a life insurance policy I didn’t need because a persuasive agent convinced me it was essential. It wasn’t. That was $87 a month I could have put toward a better health plan supplement. Write down only the categories where going uninsured would cause genuine financial harm. For most people on fixed incomes, that list is health, home or renters, and possibly auto. Everything else is worth questioning.
Step 2: Understand Medicare and Medicaid Inside and Out
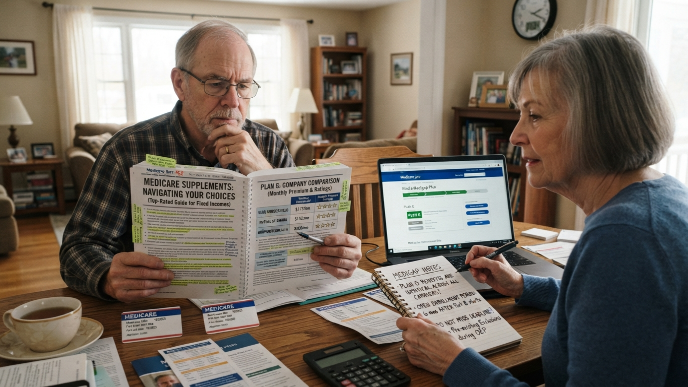
If you’re 65 or older, Medicare is your foundation. But “Medicare” isn’t one thing. It’s a patchwork, and the gaps can cost you thousands if you aren’t paying attention.
Original Medicare (Parts A and B) covers hospital stays and doctor visits, but it doesn’t cover everything. Prescription drugs require Part D. Dental, vision, and hearing? Not included in Original Medicare at all. That’s where Medicare Advantage plans (Part C) or Medigap supplemental policies come in.
I enrolled in a Medicare Advantage plan through UnitedHealthcare a few years back because the $0 premium sounded perfect. And honestly, for basic needs, it worked well. But when I needed a specialist outside the network, I hit a wall. If you have ongoing health conditions that require specific doctors, a Medigap policy (like Plan G or Plan N) paired with Original Medicare often gives you more freedom, though premiums run higher.
If You’re Under 65
Medicaid eligibility varies wildly by state. If your fixed income falls below certain thresholds, you might qualify for full Medicaid coverage, which often costs nothing out of pocket. Check your state’s Medicaid website or call your local Area Agency on Aging. They process these questions daily and can tell you in minutes whether you qualify. I called mine on a Tuesday afternoon and had an answer before dinner.
Step 3: Shop for Supplemental Health Coverage the Smart Way
A top rated insurance guide for people on a fixed income has to address supplement plans honestly, because this is where companies love to overcharge.
Medigap policies are standardized by letter (Plan A through Plan N), meaning Plan G from Blue Cross covers the exact same benefits as Plan G from Mutual of Omaha. The only difference is the price and the company’s customer service. So always compare at least three carriers for the same plan letter. Use Medicare.gov’s plan finder tool. It’s clunky, but it works.
One thing I learned the hard way: enroll during your Medigap Open Enrollment Period, the six months starting when you turn 65 and enroll in Part B. During this window, companies can’t reject you or charge more for pre-existing conditions. Miss it, and you might pay significantly more or get denied outright. Nobody told me this clearly the first time around, and I nearly missed the deadline.
Step 4: Lock Down Affordable Home or Renters Insurance
Whether you own your home outright or rent an apartment, property coverage matters. A single pipe burst or break-in can wipe out savings you can’t replace on a fixed income.
For homeowners, bundling your home and auto policies with one carrier usually saves 10 to 25 percent. State Farm, USAA (if you’re a veteran), and Erie Insurance consistently rank well for affordability and claims satisfaction. But don’t just auto-renew every year. I switched from Allstate to Erie two years ago and saved $340 annually for nearly identical coverage. That took one afternoon of phone calls.
For renters, a basic policy from Lemonade or Toggle runs as low as $5 to $15 per month. It covers your belongings and provides liability protection if someone gets hurt in your apartment. I genuinely don’t understand why more renters skip this. For the cost of a streaming subscription, you protect everything you own.
Raise Your Deductible Strategically
If you have an emergency fund, even a small one, raising your deductible from $500 to $1,000 can drop your premium noticeably. Just make sure you can actually cover that deductible if something happens. Don’t raise it to $2,500 to save $12 a month if paying $2,500 would destroy you.
Step 5: Get Auto Insurance Without Overpaying
Auto insurance is mandatory in almost every state, and it’s one of the easiest places to overspend. Companies count on you not shopping around.
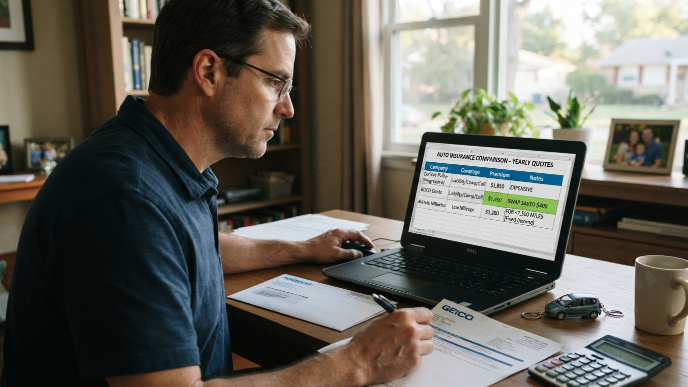
I quote my auto insurance every single year. Every. Single. Year. Two years ago, GEICO beat my existing Progressive policy by $400 for the same coverage limits. Last year, Progressive came back lower. Loyalty discounts are mostly a myth. The real savings come from being willing to switch.
If you drive less than 7,500 miles a year, ask about low-mileage discounts. Programs like Nationwide’s SmartMiles or Allstate’s Milewise charge you partly based on how much you actually drive. For someone on a fixed income who isn’t commuting to work, this can cut costs significantly.
Also, drop comprehensive and collision coverage on vehicles worth less than $4,000. The math stops making sense. You’ll pay more in premiums over two years than the car is worth.
Step 6: Consider Whether You Need Life Insurance at All
This is the section most guides get wrong. They assume everyone needs life insurance. On a fixed income, that assumption can cost you money you can’t afford.
Ask yourself one question: if you died tomorrow, would anyone face financial hardship because your income stopped? If your spouse depends on your Social Security or pension, a small term life policy makes sense. If you’re single with no dependents and no debts that would pass to anyone else, life insurance is likely unnecessary.
If you do need coverage, term life is almost always cheaper than whole life. A healthy 65-year-old can find a 10-year term policy for $50 to $100 per month through carriers like Mutual of Omaha or New York Life. Whole life policies cost three to ten times more and include an investment component that rarely performs well enough to justify the expense. I dropped a whole life policy in 2021 and redirected that money toward a better Medigap plan. Best financial decision I made that year.
Step 7: Use Every Discount and Assistance Program Available
You’d be surprised how many discounts exist specifically for seniors and fixed-income households. Nobody advertises them loudly.
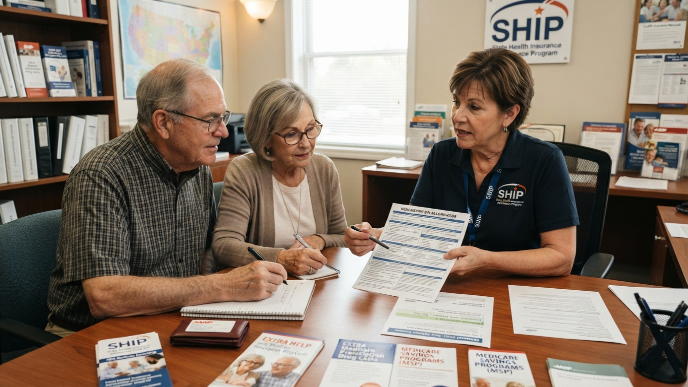
State Health Insurance Assistance Programs (SHIP) offer free counseling in every state. These counselors help you compare Medicare plans, find Extra Help for prescription drug costs, and identify benefits you might be missing. I sat with a SHIP counselor for 45 minutes and she found me a Part D plan that saved $1,200 a year on my medications. Free. No strings.
The Medicare Savings Programs (MSP) can pay your Part B premium if your income and assets fall below certain levels. That’s roughly $175 per month back in your pocket in 2024. Many people qualify and never apply because they don’t know it exists.
For auto and home insurance, ask about discounts for being claims-free, installing security systems, taking a defensive driving course, or being a member of AARP. These small reductions add up when every dollar counts.
Common Mistakes Fixed-Income Households Make With Insurance
I’ve made most of these myself, so no judgment here.
Paying monthly instead of semi-annually or annually almost always costs more due to installment fees. If you can swing a lump payment, do it. Keeping coverage you no longer need, like collision on an old car or life insurance with no dependents, drains money silently. And auto-renewing without comparing quotes is probably the most expensive habit in personal finance.
One more: ignoring the appeals process. If Medicare or your insurer denies a claim, appeal it. Roughly 50 percent of Medicare appeals succeed on the first try, according to data from the Center for Medicare Advocacy. That denied claim might not actually be denied if you push back.
Frequently Asked Questions
What’s the best type of health insurance for someone on a fixed income?
Medicare combined with a Medigap supplement or a Medicare Advantage plan covers most needs affordably. If your income is low enough, Medicaid might cover everything at no cost. The “best” option depends on your health conditions, preferred doctors, and prescription needs. A SHIP counselor can help you compare plans for free in about an hour.
Can I get insurance help if I only receive Social Security?
Absolutely. Programs like Medicare Savings Programs, Extra Help for prescriptions, and Medicaid are specifically designed for people with limited income. Social Security income counts toward eligibility calculations, but many people receiving only Social Security still qualify. Contact your local SHIP office or Area Agency on Aging to check.
Is a top rated insurance guide for people on a fixed income different from general insurance advice?
Yes, because general advice assumes budget flexibility. Fixed-income guidance focuses on minimizing premiums, maximizing government assistance programs, and eliminating unnecessary coverage. The priorities shift from “get the best plan” to “get the right plan you can actually sustain month after month without financial stress.”
How often should I review my insurance policies?
Review everything at least once a year, ideally during Medicare Open Enrollment (October 15 to December 7) and before your auto or home policy renews. Plans change their costs and networks annually. What worked last year might cost more this year. I block off one weekend in October and do all my comparisons at once.
Should I use an insurance broker or shop on my own?
Both work. Independent brokers can compare multiple carriers quickly and don’t charge you directly since they earn commissions from insurers. But always verify their recommendations against Medicare.gov or your state’s insurance marketplace. I use a broker for auto and home but handle Medicare decisions myself with SHIP counselor guidance.
Conclusion
Finding affordable insurance on a fixed income isn’t about settling for less coverage. It’s about knowing exactly what you need, cutting what you don’t, and taking advantage of programs that exist specifically to help. I spent years paying too much before I figured this stuff out, and honestly, I wish someone had just been straight with me from the start. What’s the one insurance expense you’ve been meaning to take a harder look at?